Can a 17-Year-Old Really Get Car Insurance in Their Name
Yes, a 17-year-old can get car insurance in their name, but it comes with challenges. Most insurers require a parent or guardian on the policy, and rates are higher for teen drivers. Car insurance for minors is possible through specific programs and strategies that can save money.
This is a comprehensive guide about Can a 17-Year-Old Get Car Insurance in Their Name?.
Key Takeaways
- Yes, it is possible: A 17-year-old can obtain car insurance, though most policies require a parent or guardian.
- Costs are higher: Teen drivers face some of the highest insurance rates due to lack of experience.
- Adding to a parent’s policy is cheapest: Most families save money by adding a teen to an existing policy rather than buying a separate one.
- Good grades help: Many insurers offer discounts for students with a GPA of 3.0 or higher.
- Multiple options exist: From standalone policies to being listed on a parent’s plan, there are several paths to explore.
[FEATURED_IMAGE_PLACEHOLDER]
So you just turned 17, and you are itching to hit the road. Maybe you saved up for a car, or maybe a family member is ready to hand over the keys. Either way, one question keeps popping up: can a 17-year-old get car insurance in their name? The short answer is yes. But the full story is a bit more complicated than that.
Car insurance for a 17-year-old is not the same as it is for a 30-year-old. Insurance companies view teen drivers as high-risk. That means higher premiums, more restrictions, and a few extra hoops to jump through. But here is the good news. With the right approach, you can get covered without breaking the bank.
This guide walks you through everything you need to know. From understanding why rates are steep to exploring ways to save, we have you covered. Whether you are a 17-year-old looking to buy your own policy or a parent trying to figure out the best path, this article breaks it all down.
Can a 17-Year-Old Get Car Insurance in Their Name?
The legal answer is yes. In most states, a 17-year-old can own a car and purchase insurance in their name. However, most insurance companies require a parent or legal guardian to co-sign the policy. This is because minors generally cannot enter into legally binding contracts on their own.
Some insurers do offer standalone policies for teens. But these are rare and often come with higher premiums. The more common route is being listed on a parent’s policy. This approach is not only more accessible but also significantly cheaper in most cases.
It is worth noting that laws vary by state. Some states have specific rules about teen driver insurance and what coverage a 17-year-old must carry. Before you start shopping around, check your state’s requirements. This will give you a clear picture of what is legally required and what is optional.
Why Do Insurers Treat 17-Year-Olds Differently?
Insurance companies base rates on risk. And statistically, 17-year-old drivers are among the highest-risk group on the road. According to the Insurance Institute for Highway Safety, teen drivers are more likely to be involved in accidents than any other age group. This is due to inexperience, distracted driving, and risk-taking behavior.
Because of this data, insurers charge more to insure young drivers. A 17-year-old can expect to pay nearly double what a 25-year-old pays for the same coverage. This is not a punishment. It is simply how the insurance industry calculates risk.
But there is a silver lining. As you gain driving experience and maintain a clean record, your rates will drop. Many insurers also offer discounts that can help bring the cost down. We will cover those in detail later in this article.
How Does Car Insurance Work for a 17-Year-Old?
Understanding how car insurance for minors works is the first step toward getting covered. The process is similar to adult insurance, but with a few key differences. Let us break it down.
Types of Coverage Available
Most car insurance policies include several types of coverage. Here is what a 17-year-old can typically expect:
- Liability Insurance: Covers damage or injury you cause to others. This is required in most states.
- Collision Coverage: Pays for damage to your car in an accident.
- Comprehensive Coverage: Covers non-accident damage like theft, vandalism, or weather events.
- Uninsured/Underinsured Motorist Coverage: Protects you if the other driver has no insurance or insufficient coverage.
- Personal Injury Protection: Covers medical expenses for you and your passengers.
Not all of these are required in every state. But liability insurance is almost always mandatory. A 17-year-old should carry at least the minimum coverage required by their state. Adding collision and comprehensive coverage is a smart move, especially if the car has value.
Can You Buy a Standalone Policy at 17?
Yes, but it is not easy. Few insurers offer standalone policies to drivers under 18. Those that do often charge very high premiums. A standalone policy means the 17-year-old is the sole policyholder and owns the car outright.
In most cases, it is more practical to be listed on a parent’s policy. The parent owns the car, and the teen is listed as a driver. This arrangement is simpler, cheaper, and widely accepted by insurers. If the teen does want their own policy, they will likely need a parent or guardian to co-sign.
How Much Does Car Insurance Cost for a 17-Year-Old?
Let us talk numbers. Insurance for a 17-year-old is expensive. On average, adding a teen to a parent’s policy increases the annual premium by $1,500 to $3,000. A standalone policy for a 17-year-old can cost even more, sometimes exceeding $5,000 per year.
But the exact cost depends on several factors. Here are the biggest ones:
- Location: Rates vary widely by state and even by zip code.
- Car Type: A safe, modest vehicle costs less to insure than a sports car.
- Driving Record: A clean record means lower rates.
- Coverage Limits: Higher coverage means higher premiums.
- Deductible Amount: A higher deductible lowers the monthly premium.
- Gender: In some states, male teens pay more than female teens.
Shopping around is essential. Different insurers use different formulas to calculate risk. One company might offer a great rate for a 17-year-old, while another charges a premium. Always compare quotes from at least three companies before making a decision.
Ways to Lower Car Insurance Costs for a 17-Year-Old
The good news is that there are many ways to reduce the cost of teen driver insurance. These tips can save hundreds or even thousands of dollars over time.
1. Add the Teen to a Parent’s Policy
This is the single most effective way to save money. A parent’s policy already has a history and a driving record that helps lower the overall risk profile. Adding a 17-year-old to an existing policy is almost always cheaper than buying a separate one.
Some parents worry that a teen’s accident will raise their rates too much. While that is possible, the cost of a separate policy for the teen is usually higher than the rate increase on a parent’s policy.
2. Maintain Good Grades
Many insurers offer a good student discount for teens who maintain a GPA of 3.0 or higher. This discount can save 10% to 25% on premiums. It is one of the easiest ways to lower costs, and it rewards hard work in school.
To qualify, the teen usually needs to submit a report card or transcript. The discount typically lasts until the driver turns 25 or graduates from high school, depending on the insurer.
3. Complete a Defensive Driving Course
A certified defensive driving course can lower insurance rates for teen drivers. These courses teach safe driving habits and demonstrate responsibility. Many insurers offer a discount of 5% to 15% for completing an approved course.
Some states also allow teens to skip points on their driving record by completing a course. Check with your state’s DMV to see if this option is available.
4. Choose a Safe, Boring Car
The type of car matters a lot when it comes to insurance. A high-performance sports car or a flashy vehicle will cost more to insure. A safe, reliable sedan or compact SUV is much cheaper.
Insurers look at safety ratings, theft rates, and repair costs when setting premiums. Choosing a car with good crash test scores and a low theft risk can make a big difference in the final price.
5. Increase the Deductible
A higher deductible means the teen pays more out of pocket in a claim. But it also lowers the monthly premium. For a 17-year-old, increasing the deductible from $500 to $1,000 can save a noticeable amount each month.
Just make sure the deductible is affordable. If an accident happens, the driver needs to be able to pay that amount without financial strain.
6. Drive Less, Pay Less
Some insurers offer low-mileage discounts. If the 17-year-old does not drive far or often, they may qualify for a reduced rate. Telematics programs, where the insurer tracks driving habits through a device or app, can also lead to savings.
Safe driving habits like avoiding hard braking, staying within speed limits, and not driving at night can all contribute to lower rates over time.
Can a 17-Year-Old Drive a Rental Car?
This is a common question for teens who want to drive a car that is not their own. The short answer is: it depends. Most rental car companies require drivers to be at least 21 years old. Some allow drivers as young as 18, but with heavy surcharges.
For a 17-year-old, renting a car is almost always a no-go. Even if the teen has insurance, rental companies have their own age restrictions. The age requirements for rental cars vary by company and location, but 17 is almost universally too young.
However, a teen can sometimes be covered under a parent’s rental car policy. If a parent rents a car and lists the teen as an additional driver, the parent’s insurance may extend to the rental. But again, this depends on the specific insurer and policy terms. Always check with the insurance company before renting a vehicle.
What Happens When a 17-Year-Old Turns 18?
Turning 18 is a big milestone for car insurance. At 18, a young driver is legally an adult. This means they can sign contracts, own a car outright, and purchase insurance without a parent’s involvement.
But turning 18 does not automatically lower insurance rates. The insurer still views an 18-year-old as a young, inexperienced driver. Rates will start to drop, but it takes time. Most insurers consider a driver to be “experienced” once they reach 25.
Here is what changes at 18:
- The teen can get a policy in their own name without a parent co-signing.
- They can choose any insurer, not just those that allow minors on their plans.
- They may qualify for more coverage options and discounts.
- They can build their own insurance history, which helps in the long run.
Parents should also know that a teen’s 17th birthday can bring a rate increase. Insurers often reclassify drivers at certain ages, and turning 17 sometimes triggers a reassessment of risk. Staying on top of these changes can help families avoid surprise premium hikes.
Common Mistakes Parents and Teens Make with Car Insurance
Avoiding common mistakes can save time, money, and headaches. Here are some pitfalls to watch out for:
- Not comparing quotes: The first quote you get is rarely the best. Always shop around.
- Choosing minimum coverage: Cheap premiums can lead to big out-of-pocket costs in an accident.
- Forgetting to list all drivers: If someone else regularly drives the car, they need to be listed on the policy.
- Ignoring discounts: Many families leave money on the table by not asking about available discounts.
- Lying about the primary driver: Misrepresenting who drives the car most is insurance fraud and can void the policy.
One mistake that is surprisingly common is not understanding the difference between being listed as a driver and being the policyholder. A parent can be the policyholder while the teen is listed as a driver. This setup provides coverage without requiring the teen to own the car or the policy.
Expert Insights on Teen Car Insurance
We spoke with several insurance professionals to get their take on the best strategies for insuring a 17-year-old. Here is what they had to say:
Start early: “The sooner you add a teen to your policy, the better,” says one agent. “Waiting until they are ready to drive can cause delays and confusion. Get them on the policy as soon as they have a permit.”
Focus on safety: “The safest car at the lowest price is the winning formula,” adds another expert. “A 10-year-old sedan with good safety ratings will always be cheaper to insure than a brand-new sports car.”
Keep the record clean: “One speeding ticket or accident can spike rates for years,” warns a third professional. “Teach your teen to drive defensively and avoid any infractions.”
These insights reinforce a simple truth: preparation and good habits are the keys to affordable insurance for young drivers.
Frequently Asked Questions
Can a 17-Year-Old Get Car Insurance Without a Parent?
It is very difficult. Most insurers require a parent or guardian to co-sign a policy for a minor. A 17-year-old cannot typically enter into a binding contract on their own. The best option is to be added to a parent’s existing policy.
What Is the Cheapest Way to Insure a 17-Year-Old?
The cheapest way is to add the teen to a parent’s policy. This leverages the parent’s driving history and existing coverage to lower the overall premium. Good student discounts and defensive driving courses can reduce costs even further.
Does a 17-Year-Old Need Their Own Policy if They Own a Car?
Not necessarily. Even if a 17-year-old owns a car, they can be listed on a parent’s policy. In fact, this is usually cheaper. The car can be titled in the teen’s name but insured under the parent’s policy. Check with your insurer to confirm their specific rules.
How Can a 17-Year-Old Build Insurance History?
Being listed on a parent’s policy is the best way to start building insurance history. As the teen grows older, they can transition to their own policy. Maintaining a clean driving record and continuous coverage are key steps in building a strong insurance history.
Are There Any Insurance Companies That Specialize in Teen Drivers?
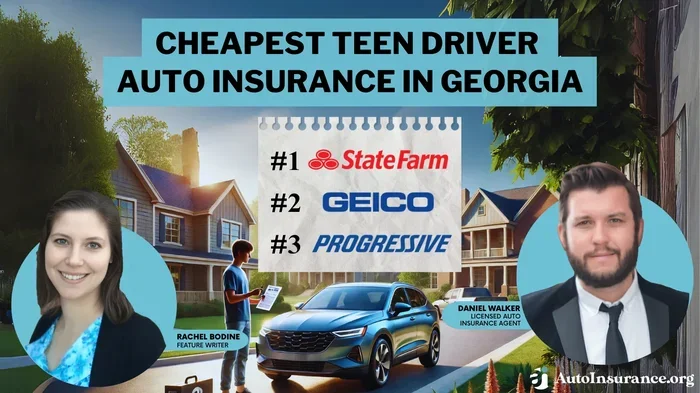
Yes, some insurers specialize in or are particularly friendly to teen drivers. Companies like State Farm, GEICO, and Progressive often offer competitive rates and discounts for young drivers. It is worth comparing quotes from multiple companies to find the best fit.
Will a 17-Year-Old’s Insurance Rates Drop After They Turn 18?
Rates may start to drop after 18, but the biggest reductions come with age and experience. Most insurers offer the best rates once a driver reaches 25. Maintaining a clean record and taking advantage of discounts can speed up the process.
Final Thoughts
The question of can a 17-year-old get car insurance in their name does not have a simple yes or no answer. It depends on the state, the insurer, and the family’s situation. But one thing is clear: it is possible, and there are smart ways to make it affordable.
The best approach for most families is to add the teen to a parent’s policy. This provides comprehensive coverage at a manageable cost. As the teen gains experience and reaches adulthood, they can explore standalone policies and build their own insurance history.
Remember, the goal is not just to get insured. It is to get the right coverage at a fair price. Take the time to compare quotes, ask about discounts, and choose a safe vehicle. These small steps can lead to significant savings over the years.
Car insurance for a 17-year-old might seem overwhelming at first. But with the right knowledge and a little planning, it is entirely manageable. Start the conversation early, stay informed, and drive safely. The road ahead is exciting, and being properly insured is the best way to enjoy it.
Frequently Asked Questions
What is Can a 17-Year-Old Get Car Insurance in Their Name??
Can a 17-Year-Old Get Car Insurance in Their Name? is an important topic with many practical applications.